
From Nepal to Sri Lanka, successive natural disasters have exposed the cost of underinvesting in water resilience.
September 3, 2026 | By Darshini Ravindranath
On November 28, 2025, satellite maps showed Cyclone Ditwah moving across Sri Lanka with dense cloud bands indicating heavy rainfall concentrations over large swaths of the country. Satellites first showed a deep depression in the Bay of Bengal that later made landfall along the eastern coast before moving inland, inundating low-lying areas and overwhelming rivers across the Central, North Central and North Western provinces. On the ground, it was one of the country’s most severe weather emergencies in decades. It triggered catastrophic flooding and landslides, with agricultural fields deluged, planting seasons dismantled and some districts receiving more than 300 mm of rainfall. Approximately 2.2 million people were affected in all 25 districts with many evacuated from their homes and fields.
More recently, on August 26 a flash flood in Nepal and Tibet led to catastrophic consequences across the northern parts of the Himalaya. Heavy monsoon rains overwhelmed river systems already swollen by glacial melt, sending floodwaters through valleys and communities with little warning. Critical infrastructure suffered severe damage, agricultural land was buried under sediment and thousands remain missing. For a country where nearly 60% of the population depends on agriculture and where mountain communities have minimal buffer against such shocks, the losses extended far beyond what any disaster-response figure can capture.
Sri Lanka and Nepal are two of many small and climate-vulnerable countries that bear the heavy burden of varying, disruptive weather patterns and longer-term climate change impacts. For climate vulnerable nations, the return on investment in models and disaster-response tools, including decision-support systems, is worth considering.
The flash flooding has left communities along the Trishuli River covered in mud and debris. Photo: Rajesh Kumar Singh/AP Photo
For years, the International Water Management Institute (IWMI) has helped governments put climate and hydrological models to work in disaster response. During Cyclone Ditwah, IWMI provided technical support to the Emergency Operations Centre (EOC) of the Sri Lankan Disaster Management Centre (DMC). The EOC operationalized IWMI’s AWARE platform for flood forecast and monitoring, while IWMI researchers provided daily integrated satellite mapping of flood inundation, tracking country level exposure on populations, buildings and agriculture. Within 24 hours of the disaster, IWMI developed a digital tool to process hard-copy rescue related police reports into digital formats, enabling Sri Lankan authorities to speed up on-the-ground rescue efforts. In Nepal, IWMI stands committed to provide technical assistance to authorities in support of immediate priorities to ensure post-event disaster risk management reaches the communities that need it most.
What does the science say?
The Intergovernmental Panel on Climate Change’s (IPCC) Sixth Assessment Report is unequivocal. Climate change is fundamentally altering the global water cycle. Precipitation is becoming more intense and more erratic, glaciers are in accelerating retreat, droughts and floods will grow more frequent and more severe. Globally, over three billion people currently experience severe water scarcity for at least one month a year. The IPCC is clear that water is the primary medium through which most people will experience the impacts of climate change.
This is no longer a distant risk. It is the present reality for countries like Sri Lanka and Nepal — a reality which bears a hefty price tag. The IPCC estimates that water-related climate risks will require adaptation investment in the hundreds of billions annually, and investment is not flowing at anything close to the required scale. Governments will need to find a way to mobilize needs-based finance to support the uptake of decision-support tools after such crises arise. And while there is no way to stop the impacts of all climate catastrophes, with anticipatory action and finance leveraged in the right way, there are sufficient tools and systems in place to systemically predict and plan for these risks.
However, some of the largest unanswered questions for countries at the forefront of addressing climate risks are those of finance and investment. Questions remain around access to finance, volume of finance, bankability of projects, risk profiles and returns on investment.
Water financing remains a missing piece
Water is sector-agnostic; the water cycle connects rainfall, groundwater, agriculture, energy, ecosystems and human health into a single interdependent system. Water is also deeply political. There is a vast body of literature on the politics of water and transboundary cooperation. Water is heavily subsidized, difficult to price and governed by overlapping mandates which make it hard for private capital to invest. The financing of water resilience thus remains largely left off the table. The water finance gap is estimated at an additional $200 billion a year, potentially tripling by 2030, and it is not closing fast enough. By 2030, global demand for water is projected to outpace supply by 40%.
To keep pace or, at the very least, follow closely behind this demand, we need to build the scaffolding for finance to flow, and four conditions offer a start.
The first is bankable value. The energy transition had two things water still lacks: a unit of account and a revenue mechanism. The megawatt-hour could be priced, insured and put on a balance sheet. Carbon markets went further and every avoided ton became a tradeable asset, generating revenue for the project while signaling risk to the market. Right now, fewer than 1% of major corporations fully understand their nature dependencies — including water. Only 26% of Fortune 500 companies have freshwater consumption targets. 44% of companies disclosing to the Carbon Disclosure Project (CDP) report substantial water-related challenges but those challenges don’t show up on balance sheets in any standardized way. If water risk were treated like carbon risk, we would have disclosure frameworks, stress-testing requirements and investor guidance built around it. We need the equivalent: a shared global framework for valuing water risk, combined with financial instruments that can make water’s value into a return. These could include payment-for-ecosystem-services and water credits tied to corporate supply chains, among others.
A collection of Nepalese Rupees. Photo: Neil Palmer for IWMI
The second is a clear political signal that changes investor expectations. The Paris Agreement in 2015 told every multilateral development bank, pension fund and infrastructure investor that the direction of travel on energy was set. Markets repriced risk and renewable energy became the default. Water has had no equivalent moment. The 2026 UN Water Conference is our best opportunity to generate that signal and aim to produce measurable, financed commitments that multilateral development banks (MDBs) and national governments can translate into lending mandates.
The third is institutional architecture. In 2024, multilateral development banks hit a record $137 billion in total climate finance, mobilizing a further $134 billion from the private sector. Clean electricity alone received $25.6 billion from MDBs to developing countries in that single year. By contrast, all MDB water commitments in 2024 totaled to only $19.6 billion.
Water receives roughly 3% to 8% of tracked global climate finance. The private sector gap is equally stark. In Africa for instance, only 9% of water investment in developing countries is private, compared to 45% in power and 87% in telecoms. Part of the explanation is that governments have not made the case from their own budgets — governments in developing countries spend around 0.5% of GDP on water — a figure that has barely shifted despite the sector’s centrality to every development outcome.
This underinvestment from governments sends a clear signal to private capital. Some MDBs have taken steps: for instance, the Asian Development Bank’s Water Financing Partnership Facility has mobilized $9.45 billion across 20 countries since 2006. At the scale of a $200 billion annual gap, these remain important but insufficient. Water still lacks a global institutional anchor equivalent to International Renewable Energy Agency (IRENA) and the Green Climate Fund, one with the mandate, capitalization and political backing to drive finance at the speed the sector needs. Concessional capital must be at its core in whatever form it takes because the countries most exposed to water insecurity are precisely the countries least able to attract commercial investment.
The fourth is the enabling environment. Finance is only as good as the enabling conditions it flows through. Fragmented project pipelines, weak off-takers, insufficient hydrological data and policy frameworks work against cost recovery. There is sufficient evidence to show that these not only slow investments down but also block it. Innovative instruments cannot succeed without functioning governance frameworks. Building the policy coherence, the regulatory frameworks and the data infrastructure that make a project bankable in the first place is less visible work, but it needs doing if we want to make finance flow. It is also work that is unlikely to find private investment, and so bilateral and multilateral actors must lead and ensure the conditions are deliberate, institutional and political.
Recent developments give reasons for cautious optimism
There are signs that the political architecture surrounding water is beginning to move. At COP29 in Baku, Azerbaijan in November 2024, 57 governments and 25 international organizations signed the Declaration on Water for Climate Action. This was the first time water has had a dedicated declaration at a climate COP. Crucially, this launched the Baku Dialogue on Water for Climate Action, a COP-to-COP platform designed to maintain continuity on water between climate conferences rather than letting it fall off the agenda the moment the plenary comes to a close. The first high-level session of the Baku Dialogue took place at COP30 in Belém, Brazil in 2025.
At the June Climate Meetings in Bonn, Germany in mid-2025 (SB62), water was explicitly recognized as a sector under the adaptation finance tracking framework — which on the face of it might not sound like much. However, it is a technical but significant step that creates a foundation for measuring and holding countries accountable for water adaptation spending for the first time.
In September 2026, IWMI and the IPCC will hold the first ever co-sponsored Expert Meeting to advance the science of water in climate change. Around 60 leading experts will gather in Colombo, Sri Lanka, to help shape the evidence for IPCC’s Seventh Assessment Report by spotlighting water’s role in climate adaptation, resilience and risk. This will help countries develop future-fit, evidence-based solutions and necessary investments for water security.
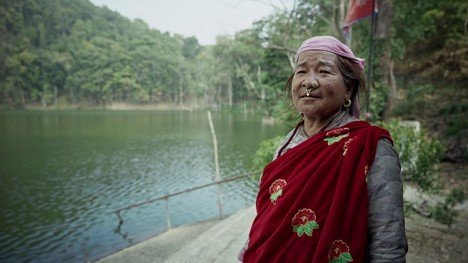
‘Benefits for people uphill meant displacement for people downhill,’ says Kheema Devi Rana, a farmer from Alital, Nepal. Photo: Aayush Niroula/IWMI
It is also important to note that in 2023, at COP28 in Dubai, UAE governments established the Fund for Responding to Loss and Damage, an overdue and hard-won recognition that some climate impacts cannot be adapted to: they can only be compensated for. Water-related disasters such as the recent ones in Sri Lanka and Nepal account for the vast majority of qualifying loss and damage events. For the Fund to reach the communities that need it most, water must be at the center of how it is operationalized and disbursed. This should not be a separate conversation from water finance but part of the same one.
These are meaningful steps. But a declaration is not a mandate, and a dialogue is not a finance window. The gap between political momentum and capital mobilization remains wide.
A call to action for the 2026 UN Water Conference on what the sector must deliver
The 2026 UN Water Conference in Abu Dhabi in December presents a significant opportunity for the water world. This is an implementation conference that opens a window for parties to be newly ambitious about what will be financed and delivered.
The science is clear, the decision support tools are tested and the water finance gap has a number against it. What remains to be seen is the political will to treat water as the climate infrastructure it has always been and help financiers understand what is truly ‘investible’. This is a prerequisite for everything else that our world depends on — food, energy, ecosystems and resilient communities.
The farmers in Sri Lanka who lost a planting season and vital income to Cyclone Ditwah, and the communities in Nepal still accounting for what was swept away just a few days ago, did not cause this problem. They are absorbing it. The finance we build for resilience, for adaptation, for loss and damage must be built with them in mind, now and in the future.
The author is a contributor at the IWMI-IPCC Expert Meeting, “Addressing Water Risks and Building Resilience to Climate Change – Evidence, Needs and Policy Pathways,” which is taking place in Colombo, Sri Lanka, from September 8-10, 2026.
Source:https://www.iwmi.org/blogs/the-water-finance-question-we-can-no-longer-ignore/
